
Yes. A bank decline does not disqualify you from funding a Florida fix and flip, because fix and flip lenders underwrite the deal and the property's after-repair value rather than your tax returns, W-2s, or bank approval history. You will pay more for that flexibility, terms run short, and the loan is built to be repaid from the sale, not held for the long haul.
Table of Contents
- What is a fix and flip loan and why do banks turn investors down?
- How fast can a fix and flip loan close in Florida after a bank says no?
- What do you need to qualify for a fix and flip loan in Florida?
- What does a fix and flip loan cost, and how does interest actually work?
- How much can you borrow in Florida, and are 100% fix and flip loans real?
- How does AberdeenFinancialGroup help Florida investors who have been declined?
- What mistakes sink a fix and flip loan after a bank decline?
- Key Takeaways
- References
What is a fix and flip loan and why do banks turn investors down?
A fix and flip loan is a short-term, interest-only loan repaid as a balloon payment from the sale proceeds of the renovated property. According to Ridge Street Capital, terms run 6 to 18 months, with 12 months the most common structure. The loan covers the purchase and renovation of a distressed property, then exits when the investor sells.
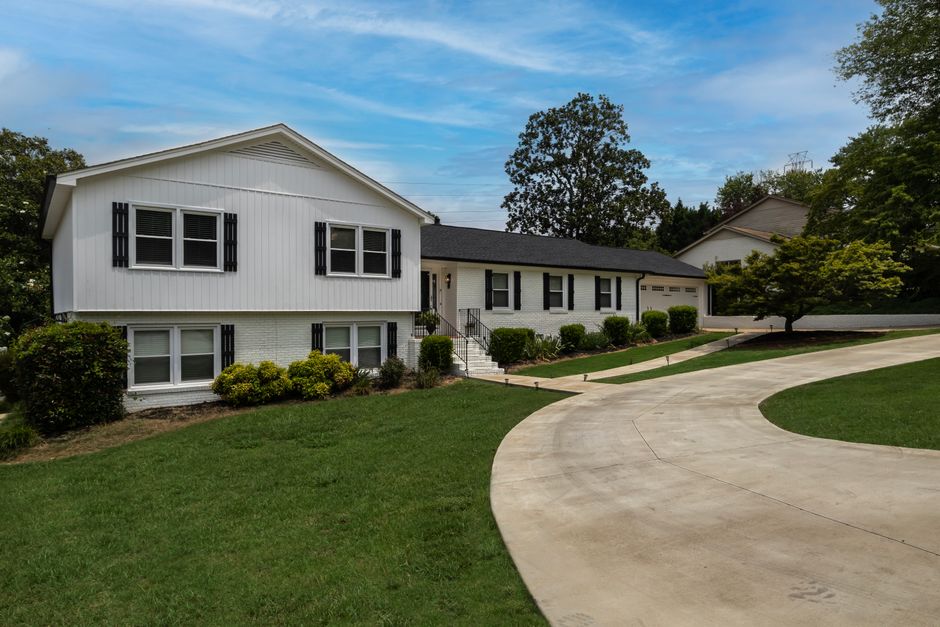
Banks turn investors down because the loan is short-term, the property is distressed, and there is no long-term income stream to underwrite. A conventional bank wants a borrower with documented income, a clean property, and a repayment schedule measured in decades. A fix and flip has none of those features. The bank's decline reflects a mismatch between the product and the borrower, not a verdict on the investor.
Hard money lenders approach the same deal differently. According to Mount Vernon Springfield, hard money lenders cash-flow the investment property rather than the individual, so borrowers do not submit tax returns and pay stubs. The lender asks whether the property can generate enough after-repair value to repay the loan. That question has nothing to do with a bank's approval formula.
How fast can a fix and flip loan close in Florida after a bank says no?
Fast enough to keep the deal alive. Conventional mortgages take 30 to 60 days to close, while many hard money or private lenders can fund a fix and flip loan in as little as one to two weeks, according to Truss Financial Group. Mount Vernon Springfield puts the typical hard money closing window at 10 to 25 days, compared with 45 to 60 days for a conventional loan. LendingOne states that fix and flip closings take 7 to 10 business days, with some files funded in as few as 5 days.

Speed matters in Florida because distressed inventory moves quickly. A seller with a damaged property and a cash buyer waiting will not hold the deal for a 45-day bank file. A slow close kills the deal.
No income verification removes the documentation bottleneck that slows bank files. LendingOne requires no W-2s or income verification for fix and flip loans. Fast does not mean instant, though. Appraisal and title work still take time, and those steps protect both the lender and the borrower.
What do you need to qualify for a fix and flip loan in Florida?
The qualification math starts with the down payment. According to Ridge Street Capital, investors can acquire a distressed property with as little as 10% down plus closing costs. The initial advance of a fix and flip loan typically covers 80% to 90% of the purchase price at closing.
Rehab funding works on a different track. Rehab funding can reach 100% of costs as long as the total loan stays below 75% of the after-repair value, or ARV. That means the lender will finance the entire renovation budget, but only if the combined purchase and rehab debt leaves enough equity in the deal to protect the lender.
Profit margin matters more than credit score. Ridge Street Capital states investors should target a minimum profit margin of 30% Return On Cash to qualify for maximum leverage. Some lenders also run first-time investor programs. Ridge Street Capital offers a High Leverage Program allowing first-time investors with strong credit to obtain 90% of purchase plus 100% of rehab on their first project.
The research does not establish a specific minimum credit score or a full list of borrower criteria such as maximum debt-to-income or minimum reserves. Mount Vernon Springfield notes that some hard money lenders fund only 50% to 70% of the purchase price, while others promote 100% purchase and 100% renovation loans but cap the loan at 70% of ARV. The qualifying question is whether the deal works, not whether the borrower fits a bank formula.
What does a fix and flip loan cost, and how does interest actually work?
The cost depends heavily on how interest accrues, and that detail quietly decides whether a deal makes money. According to Ridge Street Capital, Dutch interest accrues on the full approved loan balance from day one, including undrawn rehab funds. You pay interest on money sitting in escrow before the contractor ever touches it.
Non-Dutch interest works differently. Non-Dutch interest accrues only on funds actually disbursed, lowering carry cost while the holdback sits in escrow. That structure saves real money on a six-month rehab, because the interest clock only runs on dollars that have left the lender's account.
Exit flexibility also affects cost. LendingOne charges no prepayment penalty, which means you can exit the loan early without a penalty when the property sells ahead of schedule. The research pack does not publish specific interest rates, APRs, or origination fee percentages. Borrowers should ask for the full fee schedule before comparing offers, because two loans with the same rate can carry very different costs depending on accrual method and fees.
How much can you borrow in Florida, and are 100% fix and flip loans real?
Loan sizes start at $100,000 and reach $3 million, with up to 92.5% loan-to-cost and 100% financing on rehab costs, according to LendingOne. Those numbers sound generous, and they are, but the fine print matters.
The 100% claim needs clarification. Mount Vernon Springfield explains that some lenders promote 100% purchase plus 100% renovation loans but cap the total at 70% of ARV. Other lenders fund only 50% to 70% of the purchase price. In practice, 100% financing almost always means 100% of rehab costs, not 100% of everything. The borrower still brings the down payment and closing costs.
No-credit-check fix and flip loans are a different question. The research pack does not establish that they exist or how they would be underwritten. Fix and flip lenders typically skip tax returns and W-2s, but they still review the property, the budget, and the borrower's track record. A lender that asks no questions at all is not underwriting the deal, and that should raise more questions than it answers.
How does AberdeenFinancialGroup help Florida investors who have been declined?
AberdeenFinancialGroup positions itself as the partner businesses call when the bank says no, with a 90% approval rate and underwriting based on revenue and asset strength rather than credit score alone. For Florida investors who have been declined, the relevant products are real estate investor loans for fix and flip, ground up construction and bridge loans, working capital to increase revenue, acquire or expand operations or refinance existing debt, and equipment financing to acquire manufacturing, construction or office equipment. All three carry no upfront fees.
The fit is straightforward. AberdeenFinancialGroup funds from $50K to $5M, runs no hard credit pull, and builds its process for investors with non-traditional income or no collateral. A bank decline often comes down to documentation, and a lender that underwrites the asset and the revenue stream can move past that obstacle. The real estate investor loan product covers fix and flip deals directly, while working capital can cover carrying costs or bridge a gap, and Equipment Leasing & Financing" class="text-accent underline underline-offset-2 hover:text-gold-light">equipment financing handles the tools and machinery a renovation requires.
What mistakes sink a fix and flip loan after a bank decline?
Chasing the lowest rate instead of the lender most likely to actually fund the deal is the first mistake. A cheap quote that never closes costs more than a fundable one.
Underestimating rehab scope is the second. If the renovation budget misses structural issues, the ARV math stops working and leverage collapses mid-project. According to Ridge Street Capital, the profit margin target of 30% Return On Cash only holds if the budget holds.
Ignoring carry cost is the third. Dutch interest on undrawn funds quietly eats the margin, as Ridge Street Capital explains. Assuming a bank decline is permanent is the fourth. It usually reflects a product mismatch, not a borrower's ceiling.
Key Takeaways
- A bank decline does not disqualify you from a Florida fix and flip loan, because these lenders underwrite the property and the deal rather than your tax returns or W-2s.
- Fix and flip loan terms run 6 to 18 months, most commonly 12 months, and are interest-only with a balloon payment from sale proceeds.
- Investors can acquire a distressed Florida property with as little as 10% down plus closing costs, with an initial advance covering 80% to 90% of the purchase price.
- Rehab funding can reach 100% of costs as long as the total loan stays below 75% of the after-repair value.
- Dutch interest accrues on the full approved balance from day one, while non-Dutch interest accrues only on funds actually disbursed.
- Hard money fix and flip loans close in 10 to 25 days versus 45 to 60 days for a conventional loan, and some lenders fund in as few as 5 days.
- The research pack does not establish a specific minimum credit score, published interest rates, or the existence of no-credit-check fix and flip loans.
References
- Fix and Flip Loans Explained: A Complete Investor Guide — Ridge Street Capital, published 2026-01-31
- Fix and Flip Loans in Florida | Rehab & Investment Funding — Truss Financial Group
- What is a Fix & Flip Loan from a Hard Money Lender? — Mount Vernon Springfield, published 2023-05-07
- Fix And Flip Loans: Close In 5 Days, Up To 92.5% LTC — LendingOne